
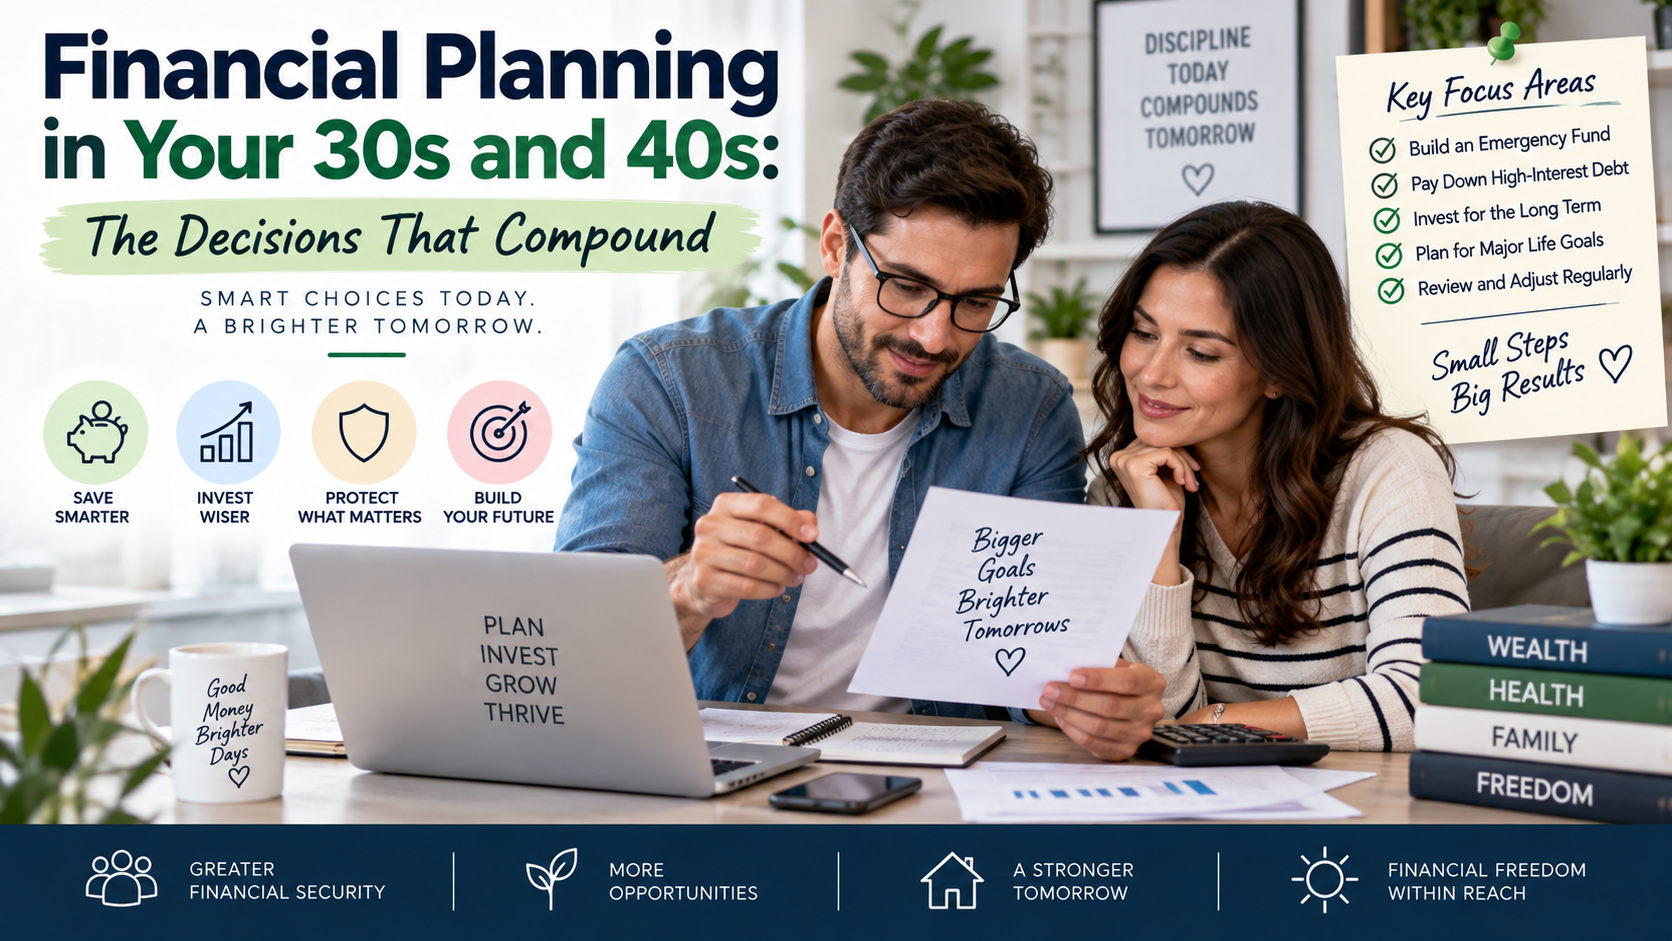
The financial decisions made between thirty and fifty carry more long-term weight than those made at any other stage, and they are made during the busiest years of most people’s lives. Careers accelerate, children arrive, homes are purchased, and parents begin needing help, all while retirement feels distant enough to postpone. The households that navigate this stretch well are not necessarily the highest earners. They are the ones who made a handful of structural decisions deliberately rather than by default.
Cash Flow Structure Beats Budgeting Willpower
The most reliable savers are not the most disciplined; they are the ones whose systems make saving automatic. Retirement contributions withheld before money reaches checking, automatic transfers to a separate savings account for known future expenses, and a genuine emergency reserve of several months of costs all remove the need for monthly willpower. Setting these structures up once produces results for decades.
Capture Every Available Match, Then Optimize Order
Employer retirement matching is the clearest return available in personal finance, and leaving it unclaimed is the most common avoidable mistake in this age group. Beyond the match, the order of savings matters: high-interest debt, emergency reserve, tax-advantaged accounts, then taxable investing, with the specific sequence depending on your tax situation and goals.
The choice between traditional and Roth contributions deserves actual analysis rather than a guess, since it depends on current versus expected future tax brackets, and this is one of many places where comprehensive financial planner services St. Petersburg FL and Tampa Bay professionals provide value that exceeds their cost.
Protect the Income That Funds Everything
In your thirties and forties, your largest asset is not your house or your portfolio. It is your future earning capacity, and it is the asset most households fail to insure. Disability coverage protects your income if you cannot work; term life insurance protects your family if you cannot be there. Both are dramatically cheaper at this age than later, and both address risks that would otherwise undo every other financial decision you have made.
Review employer coverage carefully, since group policies are often insufficient and rarely portable.
Balance Competing Goals Honestly
This stage forces genuine trade-offs: retirement versus education funding, paying down the mortgage versus investing, lifestyle now versus security later. There is no universal answer, but there is a useful principle. Retirement can be funded only by you, while education has other funding paths available. Households that sacrifice retirement savings entirely for education funding frequently regret it, and their children inherit the consequence decades later.
Build the Foundation for Later Complexity
Finally, this is when the habits and structures that serve the next thirty years get established: an annual financial review, updated estate documents and beneficiary designations, coordinated investment strategy, and a relationship with a professional if your situation warrants one.
None of these decisions feels urgent in the moment, which is exactly why they get postponed. Their power comes from time, and time is the one input you cannot recover later. Making them deliberately in this decade is what separates households who arrive at retirement with options from those who arrive with regrets.
